Search This Blog

amaz


Showing posts with label LEARNING.. Show all posts

Wednesday, April 8, 2026

भारतीय संविधान Prepare For Exams (SSC/RRB/UPSC etc.,)

CONSTITUTION / SAMVIDHAN OF INDIA
भारतीय संविधान Prepare For Exams (SSC/RRB/UPSC etc.,) 


Friday, July 25, 2025

10×12×30 के SIP फॉर्मूले में छिपा है निवेश का जादू, अब 50 हजार सैलरी वाले भी बना पाएंगे 3 करोड़ का फंड

 10×12×30 के SIP फॉर्मूले में छिपा है निवेश का जादू, अब 50 हजार सैलरी वाले भी बना पाएंगे 3 करोड़ का फंड


अगर आपकी सैलरी 50 हजार रुपए है और आप हर महीने 10 हजार की SIP करते हैं, तो 30 साल में आप 12% रिटर्न पर करीब 3 करोड़ रुपए का फंड बना सकते हैं.

अगर आप सोचते हैं कि करोड़ों का फंड तैयार करने के लिए बड़ी सैलरी या बड़ा बिज़नेस चाहिए, तो अब सोच बदलने की ज़रूरत है. म्यूचुअल फंड में SIP के जरिए एक मिडल क्लास व्यक्ति भी लॉन्ग टर्म में करोड़ों का फंड बना सकता है.

खासतौर पर, अगर आपकी सैलरी 50 हजार रुपए महीना है और आप उसमें से सिर्फ 10 हजार रुपए हर महीने SIP में लगाते हैं, तो आप 30 साल में 3 करोड़ रुपए से भी ज्यादा का फंड तैयार कर सकते हैं.

SIP का 10×12×30 फॉर्मूला क्या है?

इस फॉर्मूले को समझना बेहद आसान है. इसका मतलब है, 10 हजार रुपए हर महीने निवेश करना है 30 सालों तक, यानी कुल निवेश 36 लाख का. अगर आप हर महीने 10 हजार रुपए म्यूचुअल फंड की SIP में निवेश करते हैं, तो सालाना आपका निवेश 1.2 लाख रुपए होगा. 30 साल में यह निवेश कुल मिलाकर 36 लाख रुपए बन जाएगा.

अब मान लीजिए कि इस SIP पर आपको सालाना 12% का रिटर्न मिलता है, जो अच्छे इक्विटी म्यूचुअल फंड्स में लंबी अवधि के लिए एक व्यवहारिक अनुमान है तो कंपाउंडिंग की ताकत से यह 36 लाख का निवेश बढ़कर 3,08,09,732 का फंड बन जाएगा.

रिटर्न कितना और कैसे मिला?

इस उदाहरण में कुल निवेश 36 लाख रुपए है. लेकिन आपको मिलने वाला रिटर्न लगभग 2.72 करोड़ रुपए है. यह सारा फर्क कंपाउंडिंग की वजह से आता है. कंपाउंडिंग का मतलब है कि आपके पैसे पर जो ब्याज मिलता है, अगली बार उस ब्याज पर भी ब्याज जुड़ता है. जब आप SIP को लंबे समय तक लगातार करते हैं, तो यह कंपाउंडिंग साल दर साल बढ़ती जाती है. यही कारण है कि शुरुआत में पैसा धीरे-धीरे बढ़ता है, लेकिन 15-20 साल बाद यह तेजी से बढ़ता है.

50 हजार की सैलरी में 10 हजार की SIP कैसे संभव?

बहुत से लोगों को लगता है कि उनकी सैलरी कम है, तो वे SIP नहीं कर सकते. लेकिन 50 हजार रुपए महीने की सैलरी में 10 हजार की SIP करना पूरी तरह मुमकिन है, अगर आप अपने खर्चों की प्लानिंग थोड़ा समझदारी से करें. जरूरत की चीज़ों और फालतू खर्चों के बीच फर्क समझिए. खाने, रहने और EMI के बाद अगर आप 20% भी बचा पाएं, तो वह SIP के लिए काफी है. एक बार आदत बन जाए तो धीरे-धीरे इसमें और इजाफा भी किया जा सकता है.

अपना Mutual Fund SIP स्टार्ट शुरू  करने के लिए यहाँ क्लिक करें

(डिस्‍क्‍लेमर: यहां स्‍टॉक्‍स में निवेश की सलाह ब्रोकरेज हाउस द्वारा दी गई है. ये जी बिजनेस के विचार नहीं हैं. निवेश से पहले अपने एडवाइजर से परामर्श कर लें.)

Sunday, June 22, 2025

हर माह 7 हजार एसआईपी या 5 लाख के एकमुश्त निवेश से जुटाएं 20 लाख

हर माह 7 हजार एसआईपी या 5 लाख के एकमुश्त निवेश से जुटाएं 20 लाख


अनुज एक नौकरी करते हैं। उन्हें और उनकी पत्नी रिया को बेटी मायरा के प्री-स्कूल में एडमिशन के दौरान अहसास हुआ कि बच्चों की पढ़ाई साल दर साल कितनी महंगी होती जा रही है। अनुज को अभी से अपनी बेटी की ग्रेजुएशन की पढ़ाई की चिंता सताने लगी है। वो अगर बेटी के 12वीं पास करने के बाद उसके कॉलेज की फीस को लेकर परेशान नहीं होना चाहते तो उन्हें अभी से उसके लिए फंड जुटाना शुरू करना होगा। मान लीजिए कि मौजूदा दौर में ग्रेजुएशन की पढ़ाई का खर्च करीब 10 लाख रुपए है। ऐसे में सालाना 6% महंगाई दर के हिसाब से 12 वर्षों के बाद उन्हें 20 लाख रुपए से ज्यादा यानी अभी से कम से कम दोगुनी रकम की जरूरत होगी।

किस तरह से तैयारी करनी चाहिए? अनुज के लिए एक्शन प्लान

1. अभी से एसआईपी शुरू करें बिना किसी देरी के मायरा के ग्रेजुएशन का फंड जुटाने के लिए 7,000 रुपए की मासिक एसआईपी शुरू करें। 

2. एकमुश्त निवेश का विकल्प अनुज के पास अगर फंड है तो वे एसआईपी की जगह किसी अच्छी म्यूचुअल फंड स्कीम में 5 लाख रुपए का एकमुश्त निवेश कर सकते हैं। 

3. निवेश में विविधता लाएं

लार्ज कैप, मिड कैप, फ्लेक्सी कैप और मल्टी कैप फंड जैसी कैटेगरी का हेल्दी बैलेंस बनाकर एसआईपी करें। अभी स्मॉल कैप या थीमैटिक फंड से दूर रहें।

4. 12% रिटर्न की उम्मीद करें

म्यूचुअल फंड की लार्ज कैप, मिड कैप, फ्लेक्सी कैप और मल्टी कैप स्कीम्स ने बीते वर्षों औसतन 12-14% सालाना

ग्रेजुएशन का खर्च जुटाने के लिए प्लान

विवरण                        रकम

जरूरी रकम               20 लाख रुपए है

निवेश की अवधि          12 साल

मासिक एसआईपी        7,000 रुपए

या एकमुश्त जमा          5 लाख रुपए

अनुमानित रिट्टरन         12℅ सालाना

रिटर्न दिया है। आप सालाना 12% औसत रिटर्न की उम्मीद करें। इससे भी अगले 12 साल में करीब 20 लाख रुपए जमा हो सकते हैं, जो आपका लक्ष्य है।

5. स्कूल फीस की प्लानिंग

अनुज को अपने वेतन का एक हिस्सा डेट फंड, लिक्विड फंड, आर्बिट्रेज फंड या बैंक एफडी में निवेश करना चाहिए । वह 5 लाख रुपए क़ी एकमुश्त रकम में से कुछ हिस्से का इस्तेमाल स्कूल की सालाना फीस के लिए भी कर सकते हैं। अभी शिक्षा की महंगाई दर करीब 4% है। समय के साथ खर्च ज्यादा बढ़ सकता है। अगर विदेश में पढ़ाने की योजना है तो अधिक पैसे की जरूरत होगी । मेडिकल, इंजीनियरिंग के लिए फंड की जरूरत और ज्यादा हो सकती है।

6. सुरक्षा का इंतजाम करें मायरा की शिक्षा में भविष्य में कोई वित्तीय बाधा न आए, यह पक्का करने के लिए अनुज को अपने लिए लाइफ इंश्योरेंस लेना चाहिए और एक मजबूत इमरजेंसी फंड बनाना चाहिए। 

7. पोर्टफोलियो रिव्यू करें पोर्टफोलियो को हमेशा लक्ष्यों के अनुरूप बनाए रखने के लिए समय-समय पर उसकी समीक्षा करते रहें। जरूरत पड़ने पर उसमें बदलाव या एडजस्टमेंट करें।

आज ही अपना / अपने परिवार के सदसयो का mutual fund खाता खोलें और निवेश करें! 

खाता खोलने के लिए इस लिंक 🔗 पर क्लिक करें|


अपना Mutual Fund खाता खोलने के लिए यहाँ पर क्लिक करें और SIP या Lumpsum investment या SWP की शुरुआत करें


 (ताजा खबरों के लिए आप हमारे Telegram Channel को सब्सक्राइब जरूर करें, अपने शहर का नाम भी लिखें)

Mutual Fund Distributor - Gurvinder Singh Rattan. Founder GS Wealth and Financial Services  M: 8360264310


*Disclaimer- Mutual Fund निवेश जोखिम के अधीन है कृप्या निवेश से पहले डॉक्यूमेंट ध्यान से पढ़ें


Monday, May 19, 2025

Mutual Fund SIP: :1 हजार, 2 हजार, 3 हजार और 5 हजार की SIP से कितने साल में बनेंगे 1 करोड़

Mutual Fund SIP::: 1 हजार, 2 हजार, 3 हजार और 5 हजार की SIP से कितने साल में बनेंगे 1 करोड़


Mutual Fund SIP: हेलो दोस्तों नमस्कार क्या आप SIP करते हैं, यदि हाँ तो अच्छा हैं लेकिन यदि नहीं करते हैं, तो आज हम आपको बताएंगे की कैसे आप 1000, 2000, 3000 और 5000 रुपये की SIP करके करोड़पति बन सकते हैं।

आपको बता दे अधिकांश लोग एफड़ी और आरडी में निवेश करने के बजाय म्यूचुअल फंड के जरिए एसआईपी में निवेश कर रहें हैं। ऐसा इसलिए क्युकी आरडी और एफड़ी के मुकाबले एसआईपी में तगड़ा रिटर्न के साथ कंपाउंडिंग का बहुत बड़ा लाभ मिलता हैं।

Table of Contents

Compounding का मिलता है जोरदार फायदा
गांव-कस्बे के लोग भी शुरू कर सकते हैं SIP
आजकल गाँव ग्राम के लोग भी अपने भविष्य के लिए निवेश करना शुरू कर दिए हैं, खासकर मैं मेरा नाम अरविन्द कुमार हैं मैंने साल 2023 में एसआईपी का शुरुआत किया। मैं गाँव का रहने वाला हूँ और अपने बच्चों और बुढ़ापे के लिए निवेश करना शुरू कर दिया हैं।

आप भी यदि गाँव ग्रामीण क्षेत्रों के रहने वाले हैं तो SIP शुरू करना बहुत आसान है। मोबाइल से,  ऐप से SIP शुरू की जा सकती है। हलाकी अच्छे म्यूचुअल फंड को चुनना एक चुनौती वाला काम हो सकता हैं।

इसलिए निवेश करने से पहले किसी वित्तीय सलाहकार से सालह लेना जरूरी हैं

आप नीचे दिए गए लिंक को क्लिक करके अपना SIP वाला Mutual Fund स्टार्ट कर सकते हैं! 


Contact/whatsApp: 8360264310 for guidance संपर्क करे/ whatsApp group join karein free. 
Gurvinder Singh Rattan
AMFI रजिस्टरड Mutual फंड Distributor

*subject to market risk. Read documents carefully. 

Sunday, March 30, 2025

आधा भारत नहीं जानता पैसा बनाने वाला 40x20x50 का फॉर्मूला, समझ लिया तो बना लेंगे 5 करोड़ का फंड!सीक्रेट है सबसे धांसू...

आधा भारत नहीं जानता पैसा बनाने वाला 40x20x50 का फॉर्मूला, समझ लिया तो बना लेंगे 5 करोड़ का फंड!सीक्रेट है सबसे धांसू...


कभी सोचा है कि एसआईपी में इन्वेस्टमेंट करके आप करोड़पति बन सकते हैं. जी हां बस ₹50,000 महीने की SIP से 5 करोड़ रुपये तक का फंड तैयार किया जा सकता है? लेकिन आधे से ज्यादा लोग इस बारे में शायद ना ही जानते हों. अगर 40x20x50 फॉर्मूले को फॉलो कर लिया जाए तो फिर ये मुमकिन हो सकता है.यह सीक्रेट फॉर्मूला स्मार्ट इन्वेस्टमेंट स्ट्रैटेजी का हिस्सा है, जिससे आप 20 साल में करोड़पति बन सकते हैं, तो चलिए जानते हैं कैसे  ₹50,000 के इन्वेस्टमेंट से करीब 5 करोड़ का फंड होगा जमा.

अक्सर लोगों को शेयर मार्केट की ज्यादा समझ नहीं होती है, लेकिन फिर भी आप हाई रिटर्न वाला इन्वेस्टमेंट चाहते हैं, तो ऐसे में SIP (Systematic Investment Plan) आपके लिए बेस्ट ऑप्शन हो सकता है.SIP के जरिए आप हर महीने एक तय राशि म्यूचुअल फंड में निवेश करते हैं. SIP में जोखिम कम होता है और रिटर्न शानदार मिलता है. यही कारण है कि SIP अक्सर फिक्स्ड डिपॉजिट (FD) और दूसरी पारंपरिक बचत स्कीम से ज्यादा फायदेमंद साबित होती है.

वैसे SIP में कंपाउंडिंग का फायदा अच्छा मिल जाता है, जिससे आपका पैसा तेजी से बढ़ सकता है. अगर आप भी रिटायरमेंट के लिए अच्छा फंड बनाना चाहते हैं, तो SIP का एक बेहतरीन फॉर्मूला फॉलो कर सकते हैं, जो आपको अच्छा फंड देगा.40x20x50 फॉर्मूला एसआईपी का मनी मेकिंग हो सकता है. ये फॉर्मूला बताता है कि 40 साल की उम्र तक, 20 साल तक निवेश करें और 50 गुना तक रिटर्न पाने की संभावना बन सकती है.

अगर आप आर्थिक रूप से बिना टेंशन वाला रिटायरमेंट चाहते हैं, तो फिर 40x20x50 फॉर्मूला को फॉलो करें. इसमें 40 आपकी उम्र है तो 20 साल का इन्वेस्टमेंट पीरियड, और ₹50,000 की मासिक SIP शामिल है. यानी कि 40 की उम्र में SIP शुरू करेंगे तो 20 साल तक इन्वेस्टमेंट जारी रखना होगा. कंपाउंडिंग के दम पर आपको इसमें रिटायरमेंट तक लगभग 5 करोड़ रुपये का फंड मिल सकता है

अगर आपकी उम्र 40 साल की तो फिर हर महीने ₹50,000 की SIP शुरू करें.इसमें सालभर में 6 लाख रुपये आपके निवेश होंगे. फिर इस तरह आप इस एसआईपी को 20 साल तक जारी रखेंगे. 20 साल जारी रखने पर कुल 1.20 करोड़ रुपये का निवेश हो जाएगा. लेकिन यहां कंपाउंडिंग की ताकत काम करती दिखेगी. अगर SIP पर 12-15% सालाना रिटर्न मिल सकता है, तो यह रकम बढ़कर करीब 5 करोड़ रुपये हो सकती है.

अगर आपको 12% सालाना कंपाउंडिंग रिटर्न मिलता है, तो फिर 20 साल में 1.20 करोड़ के निवेश पर 3.79 करोड़ रुपये बस रिटर्न के रूप में जुड़ सकते हैं.यानी कुल फंड 4.99 करोड़ रुपये तक हो जाएगा.यह सब कमाल 40x20x50 फॉर्मूले की ताकत से ही होगा.जिससे रिटायरमेंट के बाद आप टेंशन फ्री हो जाएंगे.यह फॉर्मूला नौकरीपेशा और बिजनेस करने वाले सभी लोगों के लिए मनी मेकिंग है.

SIP लेने से पहले समझ लें कि इस पर रिटर्न 12% से ज्यादा या कम हो सकता है.ऐसे में निवेश से पहले सही फंड का चुनाव बेहद जरूरी होता है. हमेशा फंड का पिछला रिकॉर्ड जरूर जांचें और उसका रिटर्न आदि समझें. अगर सही फंड चुनने में दिक्कत हो रही है, तो फाइनेंशियल एडवाइजर की मदद लें.(नोट: खबर सामान्य जानकारी पर आधारित है)


Sunday, September 1, 2024

Mutual Fund SIP से जुड़ी 6 बड़ी गलतफहमियां, स्मार्ट इनवेस्टर बनना है तो इनके बारे में जान लें सच

Mutual Fund SIP से जुड़ी 6 बड़ी गलतफहमियां, स्मार्ट इनवेस्टर बनना है तो इनके बारे में जान लें यह सच

 Mutual Fund SIP की लोकप्रियता के बावजूद इनके   बारे में पूरी जानकारी की कमी है. SIP से जुड़ी ऐसी कई   गलत   धारणाएं  हैं, जिन्हें दूर करना स्मार्ट इनवेस्टर   बनने  के लिए जरूरी है.


 Mutual Fund SIP Myths Busted for   Smart Investing : सिस्टमेटिक इन्वेस्टमेंट प्लान (SIP) ने बहुत सारे भारतीय निवेशकों के लिए निवेश का तरीका बदल दिया है. म्यूचुअल फंड में इनवेस्ट करने वाले लोग बड़े पैमाने पर एसआईपी का इस्तेमाल करने लगे हैं. लेकिन एसआईपी की लोकप्रियता के बावजूद इनके बारे में पूरी जानकारी की कमी अब भी बनी हुई है. SIP से जुड़ी ऐसी कई गलतफहमियां (Myths) हैं, जिन्हें दूर करना स्मार्ट इनवेस्टर बनने के लिए जरूरी है. 

गलतफहमी 1 : SIP इनवेस्टमेंट प्रोडक्ट है

बहुत से निवेशक SIP को एक अलग इनवेस्टमेंट प्रोडक्ट मान लेते हैं. लेकिन असल में, SIP कोई इनवेस्टमेंट प्रोडक्ट नहीं है, बल्कि यह एक सुविधाजनक और अनुशासित तरीका है, जिसके जरिये आप म्यूचुअल फंड्स में नियमित रूप से निवेश कर सकते हैं. SIP के माध्यम से, एक निश्चित रकम हर महीने, हर तीन महीने में या किसी भी तय समय पर आपके बैंक खाते से कटकर आपके चुने हुए म्यूचुअल फंड में इनवेस्ट की जाती है.

गलतफहमी 2 : SIP अलग एसेट क्लास है 

यह ध्यान रखना जरूरी है कि SIP कोई अलग एसेट क्लास नहीं है और न ही इसके जरिये निवेश करने का मतलब किसी खास रिटर्न की गारंटी है. इसका प्रदर्शन पूरी तरह से उस म्यूचुअल फंड स्कीम के प्रदर्शन पर निर्भर है, जिसे आपने चुना है. इसलिए SIP को एक एसेट क्लास मानने की बजाय इसे सिर्फ निवेश प्रक्रिया को आसान और ऑटोमेटेड बनाने का एक तरीका मानना चाहिए. कुछ-कुछ वैसे ही, जैसे पोस्ट ऑफिस या बैंक के रिकरिंग डिपॉजिट होते हैं

गलतफहमी 3: SIP केवल छोटे निवेशकों के लिए है

यह बात तो सच है कि अधिकांश स्कीम्स में आप SIP के जरिये हर महीने महज 1000 रुपये या 500 रुपये जैसी छोटी रकम से भी निवेश शुरू कर सकते हैं. लेकिन इसका मतलब यह नहीं है कि SIP केवल छोटे निवेशकों के लिए है. हकीकत तो यह है कि SIP में निवेश की कोई ऊपरी सीमा नहीं होती है. कई हाई नेटवर्थ वाले लोग (HNIs) भी SIP के जरिये बड़ी-बड़ी रकम का निवेश करते हैं, ताकि रेगुलर इनवेस्टमेंट करके एवरेजिंग और कंपाउंडिंग का लाभ ले सकें. दरअसल, SIP का बड़ा फायदा यह है कि इसके जरिये म्यूचुअल फंड में निवेश करने पर आप बाजार के उतार-चढ़ाव का फायदा बेहतर ढंग से उठा सकते हैं. क्योंकि जब बाजार नीचे होता है, तो आपको उतनी ही रकम के लिए फंड की अधिक यूनिट्स मिलती हैं और जब बाजार ऊपर होता है, तो कम यूनिट्स मिलती हैं. इससे निवेश की औसत लागत कम हो जाती है. इसी को रुपी-कॉस्ट एवरेजिंग (Rupee-Cost Averaging) कहा जाता है

गलतफहमी 4: SIP केवल इक्विटी फंड्स के लिए है

यह मान्यता भी बिल्कुल गलत है कि SIP केवल इक्विटी फंड्स के लिए ही होती है. दरअसल SIP का उपयोग आप डेट फंड्स (Debt Funds) या हाइब्रिड फंड्स से लेकर गोल्ड ईटीएफ तक, हर तरह की स्कीम में निवेश के लिए कर सकते हैं. SEBI की तरफ से मान्यता प्राप्त म्यूचुअल फंड्स में इक्विटी और डेट दोनों तरह की स्कीम्स होती हैं, जिनमें से आप अपनी जरूरत के हिसाब से सही स्कीम का चुनाव कर सकते हैं. डेट फंड्स में SIP के माध्यम से निवेश करना, काफी हद तक बैंक में रेकरिंग डिपॉजिट (RD) के जरिये निवेश करने जैसा होता है, जिसमें ज्यादा रिटर्न मिलने की उम्मीद रहती है. डेट फंड्स आमतौर पर इक्विटी फंड्स की तुलना में अधिक स्थिरता देते हैं, इसलिए वे उन निवेशकों के लिए सही हैं, जो जोखिम से बचना चाहते हैं या जिनके इनवेस्टमेंट का फाइनेंशियल गोल शॉर्ट टर्म है.

गलतफहमी 5: SIP से पैसे निकालना मुश्किल होता है

कई निवेशकों को यह गलतफहमी भी रहती है कि SIP शुरू करने के बाद आप अपने पैसों को जब चाहें, निकाल नहीं सकते हैं. यह बात पूरी तरह सच नहीं है. हां, टैक्स सेविंग से जुड़े नियमों के कारण इक्विटी लिंक्ड सेविंग्स स्कीम्स (ELSS) में 3 साल का लॉक-इन पीरियड जरूर होता है, लेकिन ज्यादातर ओपन-एंडेड म्यूचुअल फंड्स में आप अपने निवेश को कभी भी निकाल सकते हैं. इतना ही नहीं, अगर आपको एक बार SIP शुरू करने के बाद किसी भी वजह से उसे रोकना है, तो आप यह काम भी आसानी से कर सकते हैं. इसके लिए आपको कोई एक्सट्रा फीस भी नहीं देनी पड़ती है. इसके साथ ही आप पहले से इनवेस्ट की गई यूनिट्स को बेच भी सकते हैं. हालांकि ऐसा करते समय एग्जिट लोड और मुनाफे पर लागू टैक्स की जानकारी ले लेनी चाहिए. एग्जिट लोड आपकी म्यूचुअल फंड यूनिट के होल्डिंग पीरियड के हिसाब से अलग-अलग हो सकता है. 

गलतफहमी 6 : SIP के जरिये सिर्फ लॉन्ग टर्म निवेश कर सकते हैं

यह मान्यता भी पूरी तरह सही नहीं है कि SIP के जरिये निवेश सिर्फ लंबी अवधि के लिए ही किया जा सकता है. हालांकि इक्विटी फंड्स में निवेश करने वालों को आम तौर पर यह सलाह दी जाती है कि वे 5-7 साल या उससे ज्यादा समय तक रेगुलर SIP करें, तभी उन्हें अपने इनवेस्टमेंट पर एवरेजिंग और कंपाउंडिंग का पूरा लाभ मिलेगा. लेकिन आप अपने निवेश के उद्देश्य के हिसाब से कम अवधि के लिए भी एसआईपी कर सकते हैं. हां, आपको अपने निवेश की अनुमानित अवधि के हिसाब से सही प्रोडक्ट का चुनाव करना होगा. मिसाल के तौर पर कम अवधि के लिए आप अल्ट्रा शॉर्ट ड्यूरेशन या शॉर्ट ड्यूरेशन फंड जैसे किसी डेट फंड में SIP के जरिये निवेश कर सकते हैं. 


CLICK HERE -TO Open Your Mutual Fund Account and Invest with AMFI Registered Mutual Fund Distributor

Also Read

Why you should have Multi Asset Allocation Funds in your portfolios? 


Why you should have Multi Asset Allocation Funds in your portfolios

Why you should have Multi Asset Allocation Funds in your portfolios? 


Why is asset allocation important?

In investing, risk and returns are correlated. You need to balance risk and returns, so that you are able to achieve your investment objectives without taking unnecessary risks. Asset allocation balances risk and returns of diversifying your investments over different asset classes e.g. equity, fixed income, gold, real estate etc. Each asset class has an important and unique role to play in your investment portfolio.

Role of different asset classes in your portfolio

  • Equity: The primary investment objective for equity as an asset class is capital appreciation and wealth creation. Historical data shows that equity as an asset class has the potential to create wealth over long investment horizons. However, equity can be volatile in the short term.

  • Fixed income: Fixed income or debt may generate relatively stable returns. Since fixed income as an asset class is relatively less volatile compared to equity, they are suited for a variety of investment tenures, from a few days to several years.

  • Gold: From time immemorial, gold is considered to be a store of value because it is able to retain its purchasing power over time. In other words, gold is seen as a hedge against inflation.

  • Other asset classes: Apart from the 3 common asset classes mentioned above, other asset classes like silver, real estate, international equities etc. can also play unique roles in diversifying your portfolio

Investor behaviour in market cycles

Equity and gold exhibit cyclicality in their returns. Behavioural biases (e.g. greed and fear) get exposed in market cycles. For example, in bull markets, investors keep investing at higher and higher prices in the hope that prices will rise further. In bear markets, investors sell even at very low prices because they fear that price may fall further. These behavioural biases harm the financial interest of the investors. Timing the market cycles is very difficult because price behaviours of different assets are driven by a variety of factors including macro-economic data, liquidity in financial markets, risk sentiments etc. So, how do we solve this jigsaw of volatility in asset classes? A multi-asset allocation strategy can bring stability to your portfolio across investment cycles.

Multi Asset Allocation Funds

Multi Asset Allocation funds are hybrid mutual fund schemes which invest in 3 or more asset classes. According to SEBI regulations multi asset allocation funds must invest minimum 10% each in at least 3 asset classes. Apart from the two most popular asset classes, fixed income and equity, these schemes can invest in asset classes like gold, silver, real estate investment trusts (REIT), infrastructure investment trusts (InvIT), international equities etc. The fund manager decides the proportional allocation to each asset class based on the market conditions with the objective of balancing risks and returns.

Low correlation of asset class returns

There is low correlation between returns of different asset classes in different market conditions; equity and gold are usually counter-cyclical to each other i.e. gold outperforms when equity underperforms and vice versa (see the chart below). Equity and gold have low correlation with debt. Gold and silver returns are usually correlated but silver tends to outperform gold in early stages of recovery. Multi Asset Allocation will keep you disciplined in your investments and provide you a more stable investment experience viz. if one asset class underperforms, the outperformance of another asset class will balance the risks


Why invest in multi asset allocation?

  • Diversification across asset classes will reduce portfolio volatility due to low correlation of asset class returns across investment cycles.

  • You do not have to guess which asset class will do well in the near term since your investments will be spread across multiple asset classes.

  • As an investor, you will be less susceptible to behavioural biases and stay disciplined in your investments.

  • Multi asset allocation funds have the potential to optimize returns at a given level of risk to ensure that investment experience is better.

  • You may get the benefit of rebalancing in multi asset allocation funds

Is this a good time to invest in multi asset allocation funds?

  • Equities have rallied in anticipation of lower interest rates in coming quarters. Equities may rally further when interest rates actually come down.

  • The rally in equities may have made valuations expensive in certain pockets of the markets.

  • Gold may continue to gain strength when interest rates come down. Traditionally, there has been an inverse relationship between gold prices and interest rates.

  • Bond yields have eased and bond prices will go up when central banks will start cutting interest rates.

  • In these market conditions a multi asset strategy can be suitable for long term investors.

Who should invest in multi asset allocation funds?

  • Investors looking for capital appreciation over long investment horizons.

  • Investors who want to reduce portfolio volatility by diversifying across multiple asset classes.

  • Investors with minimum 3 – 5 years investment tenure.

  • Investors with very high risk appetite

  • Investors can invest either in lumpsum or SIP based on their investment needs

Investors should consult their financial advisors or mutual fund distributors if multi asset allocation funds are suitable for their investment needs.

Note: Views provided above based on information available in public domain at this moment and subject to change. Investors should not consider the same as investment advice. Past performance may or may not be sustained in future and is not a guarantee of any future returns.

An Investor Education & Awareness Initiative. 

Mutual Fund Investments are subject to market risk, read all scheme related documents carefully

Interested to Invest / Open your Mutual Fund Account: http://p.njw.bz/39255

Contact: 8360264310

Registered Mutual Fund Distributor

Mutual Fund SIP से जुड़ी 6 बड़ी गलतफहमियां, स्मार्ट इनवेस्टर बनना है तो इनके बारे में जान लें सच

Wednesday, August 28, 2024

Young Girl of 15 years invents device that converts the movement of the sea into energy


Young Girl of 15 years invents device that converts the movement of the sea into energy


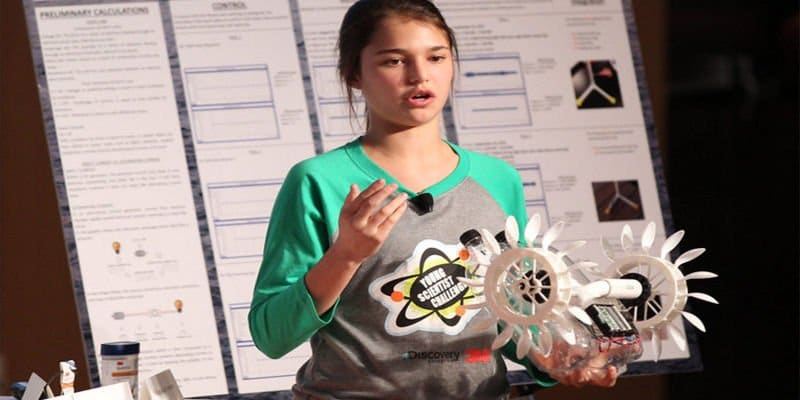
With only $ 12 of investment , Hannah Herbst bought the necessary materials to develop a device that generates renewable energy with the movement of ocean currents . The girl, who lives in Florida, won the  2015 Discovery Education 3M Young Scientist Challenge  and won $ 25,000 as a prize.
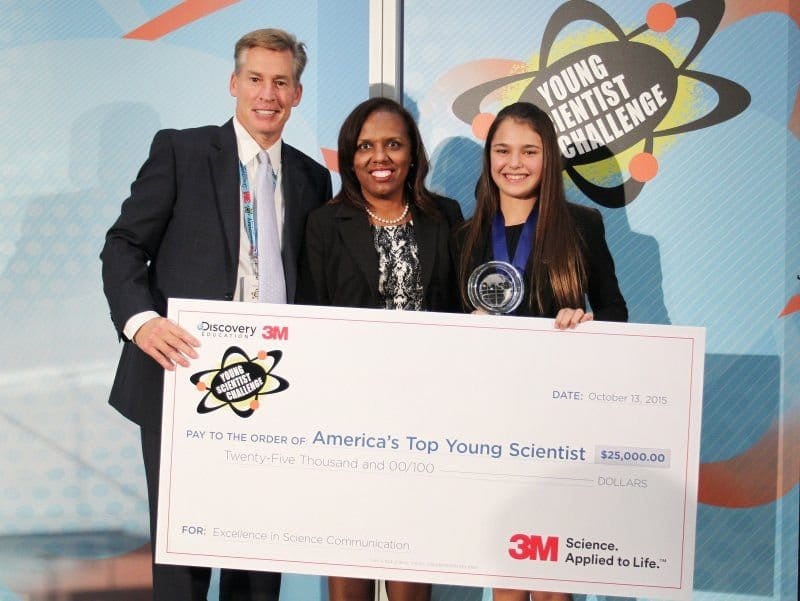
Hannah Herbst Award
To build this type of technology, Hannah uses a 3D printed propeller, some PVC pipes, a pulley and a hydroelectric generator. Her prototype produces enough energy to power an LED lamp , but she believes that if she could invest in the construction of a larger prototype, she could charge three batteries in one hour. The interest for the oceanic energy has been increased in the last years with projects of quite spread, the last one that we have known is in Australia
With this energy, it would be possible to supply enough energy for a desalination pump and filter the seawater, to convert seawater into drinking water.
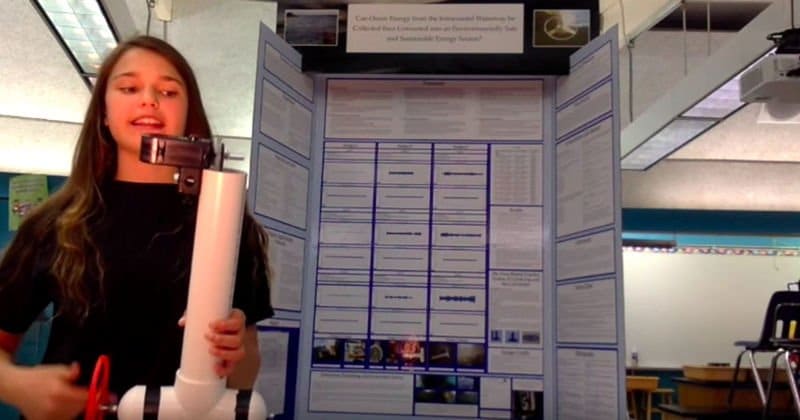
15-year-old scientist invents device that converts the movement of the sea into energy
The value of the prize is already destined: go straight to your savings to pay for college after high school. You have to admit: the girl has talent! If the future of the world depends on it, the lack of drinking water and investment in renewable energy will not be a problem for society. We are getting to know the stories of young people who, with their enthusiasm and ability, want to help develop technologies that respect the environment, such as  Boyan Slat, founder and CEO of " The Ocean Cleanup ",  an organization that will deploy the first system to safely remove plastic waste from the oceans  or  Cynthia Sin Nga Lam, which has developed the H2Pro, a device that purifies wastewater and at the same time produces hydrogen that allows generating electricity using only sunlight.
Hannah started her project while writing to a 9-year-old boy living in Ethiopia, he discovered that his family lived without a reliable source of electricity and drinking water. So Herbst invested his efforts in trying to solve the problem that had the family of that child.
In the following video, Hannah explains in her own words how her contraption works.

If you liked this article, share it with your friends in social networks Thanks    
Comments

Saturday, August 10, 2024

Large Cap, Mid Cap, or Small Cap: Which Mutual Fund is Right for You?

Large Cap, Mid Cap, or Small Cap: Which Mutual Fund is Right for You?


An Interesting Intro 

Investing in mutual funds can be a smart way to grow your wealth over time. But with countless options available, choosing the right one can be overwhelming. One key factor to consider is the size of the companies the fund invests in: large cap, mid cap, or small cap. Each type offers distinct advantages and risks. Let's break down the differences to help you make an informed decision.

Understanding Market Capitalization

Before diving into the funds, it's essential to grasp the concept of market capitalization. It's simply the total value of a company's outstanding shares.

Large-cap companies are established giants with substantial market value. Think of household names like Reliance Industries or HDFC Bank.
Mid-cap companies are growing businesses with market capitalization between large and small caps. They often exhibit strong growth potential.
Small-cap companies are relatively new and smaller companies with higher growth prospects but also higher risk.

Large Cap Funds: Stability and Steady Returns

Invest in: Established, financially sound companies.
Risk: Lower compared to mid and small-cap funds.
Returns: Generally steady and consistent, but often lower than mid and small-cap funds.
Ideal for: Risk-averse investors seeking stability and regular income.
Example: A large-cap fund might invest in companies like TCS, Infosys, and HDFC Bank.

Mid Cap Funds: Balanced Growth and Risk

Invest in: Companies with strong growth potential but not yet as large as large caps.
Risk: Moderate, higher than large cap but lower than small cap.
Returns: Potential for higher returns than large cap funds, but also more volatility.
Ideal for: Investors seeking a balance between growth and stability.
Example: A mid-cap fund might invest in companies like Bajaj Finance, Axis Bank, and Maruti Suzuki.

Small Cap Funds: High Risk, High Reward

Invest in: Young, rapidly growing companies with the potential for explosive growth.
Risk: Highest among the three, with significant price fluctuations.
Returns: Potential for the highest returns, but also the highest chance of losses.
Ideal for: Aggressive investors with a long-term horizon who can tolerate high risk.
Example: A small-cap fund might invest in companies operating in emerging sectors like biotechnology or renewable energy.

Which One is Right for You?

The best mutual fund depends on your individual financial goals, risk tolerance, and investment horizon.

Conservative investors: Prioritize stability and opt for large-cap funds.
Moderate investors: Seek a balance between growth and risk with mid-cap funds.
Aggressive investors: Aim for higher returns and are comfortable with volatility, consider small-cap funds.
Remember: Diversification is key. Consider investing in a mix of large, mid, and small-cap funds to spread risk and enhance returns.

Additional Tips

Consult a financial advisor: Seek professional guidance to tailor your investment strategy.
Long-term perspective: Mutual fund investments are generally for the long term. Avoid short-term decisions based on market fluctuations.
Regular review: Monitor your investments and rebalance your portfolio as needed.
By understanding the distinctions between large cap, mid cap, and small cap funds, you can make informed decisions to build a diversified investment portfolio that aligns with your financial objectives.


https://tinyurl.com/yze9587z?code=39255

Mutual Fund Investments are subject to market risk, read all scheme related documents carefully